Executive Summary
In M&A transactions, especially in the SME sector, negotiations often start and end with one number — the purchase price. But seasoned dealmakers know that the headline price is only one part of the equation
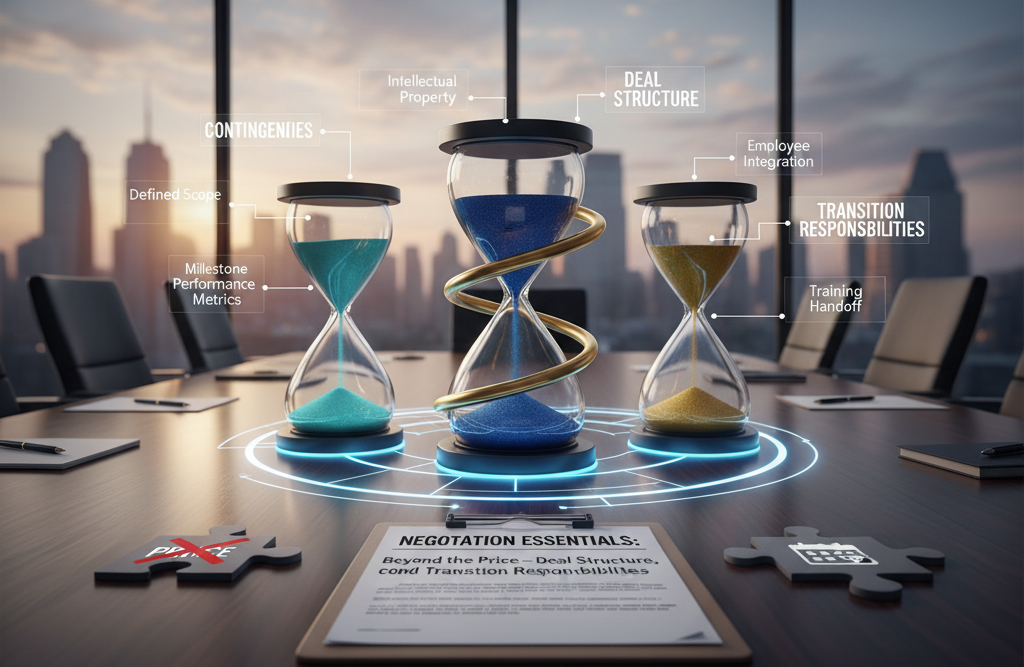
The real value of a transaction depends on how the deal is structured, what contingencies are attached, and how the transition is managed after closing. These elements determine not just what the seller receives, but when and how securely they receive it.
This article breaks down the three pillars of effective deal negotiation — structure, contingencies, and transition responsibilities — and explains how getting them right can protect both value and relationships in an SME sale.
1. The Price Illusion: Why Structure Matters More Than Numbers
The Common Trap
SME owners often fixate on a buyer’s offer price, overlooking the fact that two deals with identical prices can produce vastly different outcomes. A $5 million deal may sound attractive, but when payment terms, financing sources, and earn-out provisions are factored in, one offer could yield $4.9 million net while another delivers only $3.6 million.
Core Elements of Deal Structure
| Deal Component | Description | Impact on Value |
|---|---|---|
| Payment Terms | Cash at closing vs deferred or contingent payments | Affects liquidity and certainty for seller |
| Vendor Take-Back (VTB) | Portion of price financed by seller, usually with interest | Can bridge financing gaps but adds risk |
| Earn-Out Clauses | Future payments based on performance targets | Aligns incentives but complicates post-sale operations |
| Working Capital Peg | Adjusts purchase price for actual working capital delivered | Prevents value leakage at closing |
| Tax & Legal Structure | Asset vs share sale, jurisdictional considerations | Determines net proceeds after tax |
Example
A manufacturing SME accepted a $6.5M offer with a $1.5M earn-out over three years. However, missed integration targets—largely outside the seller’s control—meant only $5.1M was realized. A competing $6M all-cash offer would have been worth more in real terms.
2. Contingencies: Protecting Value Through Clear Conditions
What Are Contingencies?
Contingencies are conditions precedent that must be met before the transaction closes — or triggers for adjusting price post-closing. They protect both parties but can also be misused if poorly drafted.
Types of Common Contingencies
| Contingency Type | Purpose | Typical Example |
|---|---|---|
| Due Diligence | Allows buyer to verify representations | Buyer may walk away if major financial inconsistencies arise |
| Financing Approval | Gives buyer time to secure funding | Especially relevant for leveraged or VTB-financed deals |
| Regulatory/Legal | Ensures compliance with government bodies | Needed in healthcare, food, or environmental sectors |
| Performance-Based | Links part of payment to future targets | 10% earn-out tied to 12-month EBITDA threshold |
| Employee Retention | Requires key staff to remain post-sale | Buyer can renegotiate if critical personnel leave early |
Best Practices
Define contingencies precisely — vague conditions create loopholes.
Tie timelines to milestones, not open-ended approvals.
Ensure mutual accountability — both parties should have deliverables.
Example
In one Cannar M&A transaction, a buyer’s “satisfactory due diligence” clause delayed closing by two months. By revising it to “completion of financial and operational review within 30 business days,” both parties gained clarity and maintained momentum.
3. Transition Responsibilities: Securing Continuity After Closing
The Overlooked Phase
Many deals falter after signing because the human and operational handover isn’t planned. Transition responsibilities define how the business moves from seller to buyer control without disruption.
Core Transition Elements
| Responsibility | Seller’s Role | Buyer’s Expectation |
|---|---|---|
| Leadership Transition | Seller provides oversight and introductions | Continuity of client and supplier relationships |
| Knowledge Transfer | Document SOPs, train team, assist in key operations | Smooth onboarding of new leadership |
| Employee Retention | Help maintain morale and commitment | Minimize post-sale turnover |
| Customer Communication | Joint announcement and reassurance messaging | Protect client trust and contract renewals |
| Operational Support | Advisory period (3–6 months typical) | Reduces disruption and protects working capital flow |
Example
In a recent Ontario transaction, a seller stayed on for six months as “Operational Advisor.” His involvement retained all top 20 customers, avoided supplier churn, and helped the buyer achieve full performance targets in the first year — unlocking a 15% earn-out bonus for the seller.
4. The Integration Advantage
Top-performing transactions view negotiation as the start of collaboration, not the end of conflict. A well-structured deal reduces disputes and accelerates post-sale value creation.
Checklist for Balanced Negotiations
Align deal structure with strategic goals — cash flow, control, and timing.
Define contingencies clearly and avoid open-ended clauses.
Treat transition as a shared project, not an afterthought.
Use data and forecasting models to simulate scenarios and mitigate risks.
Key Takeaway
In SME transactions, negotiation isn’t about winning — it’s about designing a structure that works for both sides. A fair deal maximizes certainty, protects value, and ensures a smooth operational handover.
Price is what’s written in the contract; value is what’s realized after the ink dries.